
For months, the economic commentariat has been waiting for President Trump’s tariffs to ignite a new inflation fire. The script was already written: tariffs would raise consumer prices, the Federal Reserve would have to stay tighter for longer, and the American worker would once again pay the bill.
July’s inflation report just blew a hole through that story.
The Consumer Price Index rose only 0.1 percent in July. Core inflation, stripping out food and energy, rose just 0.2 percent. More important, core inflation over the last three months is running at only a 1.6 percent annualized rate.
That is not tariff inflation. That is price-stability territory.
The 3.4 percent headline inflation number will get the headlines, but it badly obscures what is happening underneath. The main distortion is energy. Energy prices are still 14.7 percent higher than a year ago, with gasoline up 24.6 percent, largely reflecting the oil shock associated with the conflict in Iran.
Yet even that pressure is now moving in the right direction. Energy prices fell 1.5 percent in July, and gasoline fell 2.9 percent. The three-month annualized headline CPI is just 0.5 percent.
This is precisely why the Federal Reserve should not make the classic central-bank mistake of treating an oil shock as if it were a generalized inflation spiral. You do not cure a geopolitical oil shock by crushing American factories, homebuilders, farmers, and small businesses with unnecessarily high interest rates. Higher rates will not pump one extra barrel of oil.
Look instead at the parts of the economy where tariff inflation was supposed to show up first.
Core goods prices are up only 0.8 percent from a year ago. New vehicle prices are up just 0.5 percent. Used cars and trucks are down 1.9 percent. Rental cars are down 3.9 percent. Prescription drug prices fell 0.8 percent in July and are down 3.1 percent over the year. Medical equipment and supplies are down 2.7 percent.
Across the CPI basket, prices are falling year over year for everything from used cars and prescription drugs to appliances, wireless services, health insurance, and smartphones.
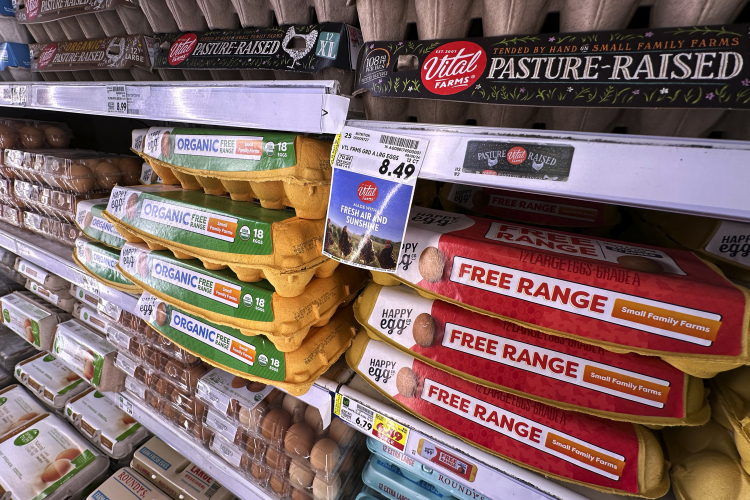
Food prices rose only 0.1 percent in July, while grocery prices actually fell 0.1 percent. Beef prices remain too high, but even beef and veal fell 0.8 percent for the month. Meat, poultry, fish, and eggs collectively fell 0.7 percent.
Then there is one of the most painful Biden-era household costs: automobile insurance.
Car-insurance inflation hit 20.6 percent in 2023. It slowed to 11.8 percent in 2024 and 0.5 percent in 2025. As of July 2026, motor-vehicle insurance prices are down 4.5 percent from a year ago.
That is not an academic statistic. Families do not live inside econometric models. They live inside monthly budgets, and this is what relief looks like.
The same story is showing up in paychecks. Real weekly earnings are rising under Trump after being squeezed by Biden inflation. Manufacturing workers have gained roughly $2,300 on an annualized basis after inflation. Construction workers are ahead by more than $3,100. Mining and logging workers are up more than $5,000. For non-managerial workers in durable manufacturing, the annualized real gain exceeds $4,500.
This is the economic combination the tariff critics insisted could not happen: strong protection for American industry, rising real wages, and decelerating underlying inflation.
There is also a broader policy lesson. America can use tariffs to defend its industrial base without accepting the false choice between factories and price stability. Tariffs alter relative prices and bargaining power. They do not mechanically create economy-wide inflation unless monetary and fiscal policy accommodate a generalized price spiral. July’s numbers show no such spiral.
None of this means every price is falling. Airline fares remain elevated. Hospital costs rose in July. Beef is still expensive. Energy remains vulnerable to geopolitical shocks.
But monetary policy is supposed to distinguish signal from noise. The signal in July is unmistakable: underlying inflation is cooling fast, tariff pass-through remains contained, and real wages are moving higher.
The Fed should read the data in front of it, not the anti-tariff forecasts behind it.
Tariffs are not setting America on fire.
The inflation scare is running out of gas.