
Markets treated the federal government’s latest inflation report as good news. Consumer prices rose 0.1% in July, bringing annual inflation down to 3.4%. Core inflation, which excludes food and energy, sits at 2.5%. Commentators spoke of "breathing room" for the Federal Reserve.
Breathing room, compared to what? Wages are growing at 3.2%, which means real earnings are shrinking. The Fed is supposed to target 2% inflation. The good news, apparently, is that inflation is only 70% above target. That’s hardly reason to be impressed.
Inflation has now run above the Fed's stated goal for more than five years. Since early 2021, prices have risen roughly 28%; had the Fed hit its target, the increase would have been about 11%. That gap is a permanent tax on savers and wage earners.
Meanwhile the Fed is beset by internal divisions. The Federal Open Market Committee’s (FOMC) July policy statement passed by a 9–3 vote. One regional Fed president publicly urges action against inflation while others eye rate cuts.
Money is the economy’s yardstick. Every contract, wage agreement, retirement plan, business forecast and government spending bill (and forecast) is denominated in dollars. When the yardstick stretches unpredictably, all these plans go awry. Entrepreneurs mistake inflationary noise for economic fundamentals, tricked into investing in projects that prove unsustainable. The economy won’t flourish without dollar stability. It’s just as essential for commerce as property rights and the legal system.
The public is losing trust in the Fed. The New York Fed's July survey put households' one-year inflation expectations at 3.6%, only slightly below June’s reading, which was the highest since 2023. More alarming, expectations at the five-year horizon sit at 3%— a full point above target. The public is concluding, reasonably, that 2% is cheap talk.
Once a central bank loses control of inflation expectations, regaining credibility is brutally expensive. Paul Volcker re-anchored expectations in the 1980s, but the cost was two recessions. Every month above target makes the eventual reckoning more difficult.
The root problem is our discretionary system of monetary policy. The Fed lacks a clear and fixed rule specifying its objectives. There are no penalties for missing its self-adopted 2% target. Don’t forget the history: starting in 2020 the Fed delivered a historic inflation overshoot, called it "transitory," and quietly revised its policy framework in 2025. Nothing to see here; move along. A private fiduciary who missed a contractual benchmark by 70% for five years would be fired, and probably sued. Fed officials who presided over the worst inflation in four decades kept their jobs, their salaries, and their slots on the speakers’ circuit.
Policy reviews won’t fix this. Personnel changes won’t fix this. Only a binding monetary rule requiring price stability, enacted in law by Congress and enforced by the President, will fix this.
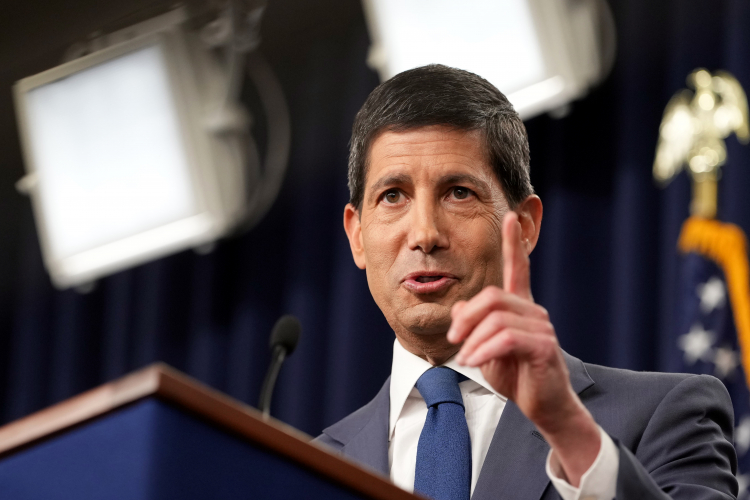
Chairman Kevin Warsh, to his credit, seems to understand the stakes of the problem. He has promised "regime change," declared that inflation is ultimately a policy choice, and launched five task forces to reexamine everything from the Fed's balance sheet to its inflation framework. He’s asking the right questions. But recommendations delivered to a discretionary body do not meaningfully constrain it. Whatever the task forces propose, the FOMC remains free to adopt, amend, or abandon. Chairmen come and go.
Sound money is too important to trust in the character of whoever holds the gavel. We need real institutional change.
The durable fix runs through Congress, in which the Constitution vests ultimate authority over monetary policy.
Legislators should amend the Federal Reserve Act.
First, replace the dual mandate with a single mandate for price stability. Define it as zero percent inflation—the claim that we need some small, positive amount of inflation to grease the economy’s wheels is nonsense. Second, attach consequences to failure. Make senior Fed officials removable for documented, persistent misses of the statutory target.
If these changes seem extreme, it’s only because of how far we’ve allowed the Fed to drift from the principles of lawful government. This is the ordinary discipline we impose on everyone else who wields delegated power. Why should central bankers get a pass?
Warsh's task forces will report by year's end. If regime change is more than a slogan, they should recommend binding rules and ask Congress to write them into law. After five years of excessive inflation, the American public has had enough with the insularity and irresponsibility of monetary technocrats. It’s time for real accountability. A stable-price mandate is how we’ll get it.