
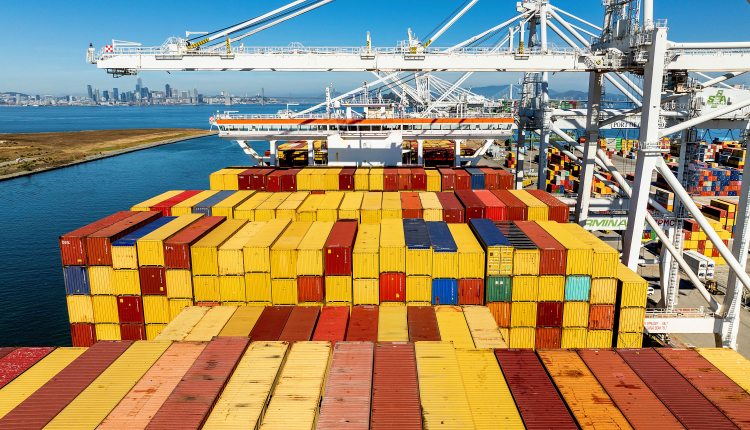
August’s ugly $105.6 billion trade deficit tells two very different stories. One begins with the Supreme Court’s February decision knocking down President Trump’s broad reciprocal tariffs and forcing the administration onto narrower trade authorities. The other is much more encouraging: America is importing extraordinary amounts of capital equipment because companies are building factories and supply chains here at home.
Start with the headline. The goods-and-services deficit jumped 13.7 percent from July, above the $102 billion Wall Street consensus. Imports rose $17.2 billion to $420.8 billion. Exports also rose, but by only $4.5 billion, to $315.2 billion. The goods deficit widened to $136.6 billion while the services surplus held at roughly $31 billion.
That sounds like a return to the old borrow-consume-import model. It is not. The import boom is overwhelmingly an investment boom, not a consumption binge.
Look under the hood. Capital goods excluding automobiles reached $146.4 billion in August—roughly 44 percent of all goods imports, the highest share on record. Even more striking, through August capital-goods imports are up $285 billion from the same period in 2025. Total goods imports, by contrast, are up only about $97 billion.
Do the arithmetic. Every other import category combined is down roughly $188 billion year-to-date. Consumer-goods imports alone are down $111 billion. Auto imports are down almost $13 billion—the Section 232 tariffs are clearly working here.
August continued that pattern. Capital-goods imports rose another $6.2 billion, led by a $2.4 billion jump in semiconductors and a $1.3 billion rise in industrial machinery. Industrial supplies rose $9.1 billion, with crude oil and nonmonetary gold accounting for much of that gain. Consumer-goods imports actually fell by about half a billion dollars.
This matters because imports are not all created equal. A finished foreign consumer product can displace American production. An imported semiconductor, turbine, machine tool, server, or piece of industrial equipment can become part of an American factory or supply chain. It worsens net exports in the GDP arithmetic today, but it can expand the domestic capital stock, productivity, and output tomorrow while reducing future imports.
The country numbers tell the same structural story. Through August, the U.S. goods balance improved sharply with the European Union, Switzerland, China, Japan, and India. The biggest deteriorations were concentrated in Taiwan, Vietnam, Thailand, Mexico, South Korea, and Malaysia—many of the economies sitting squarely in the semiconductor, electronics, machinery, and North American supply chains now feeding the U.S. investment boom.
Yet, some of those import surges also deserve scrutiny for transshipment-- Taiwan, Vietnam, Thailand, Mexico, South Korea, and Malaysia all loom large in the Great Transshipment Scam reported by my White House office.
South Korean steel exports, in particular, deserve special scrutiny. Despite President Trump’s 50 percent steel tariffs, imports of Korean steel products reached $306 million in August—nearly double their level a year earlier. That is a small slice of our $8.8 billion goods deficit with Korea, but small in the national accounts does not mean harmless to American steelmakers.
Imported rebar, structural steel, sheet, and pipe compete directly for orders that should support American mills and American workers. We need immediate, more rigorous enforcement: trace “Korean” steel to its real melt-and-pour origin, crack down on Chinese steel transshipments entering through Korea, collect every duty owed, and shut down any proven evasion. We also need a significant increase in the tariffs on South Korean steel—it is IMPOSSIBLE for the Koreans to flood our markets like they are doing without cheating.
Now for the less comfortable part of the story: the Supreme Court.
In February, the Court struck down the administration’s use of the International Emergency Economic Powers Act to impose reciprocal tariffs ranging from 10 percent to 50 percent. The White House immediately substituted a temporary 10 percent tariff under Section 122 of the Trade Act. When that authority expired in July, the administration moved to Section 301 duties of 10 percent or 12.5 percent on most imports from 60 trading partners, while Section 232 and other tariffs remained in place.
That preserved a tariff floor, but for many countries it was lower than the reciprocal rates the Court erased. It would be wrong to blame one month’s trade number mechanically on one court decision. Strong U.S. demand and the capital-investment boom are plainly major drivers. Still, the Court forced a more constrained tariff architecture onto the administration and reduced the tariff brake on some import flows at the margin.
How much might the lower tariffs matter? Penn Wharton estimated that replacing the invalidated IEEPA tariffs with the initial 10 percent levy reduced the average effective tariff rate from 10.3 percent to 7.7 percent.
Using that decline as an illustrative benchmark, and varying how strongly import demand responds, produces roughly $8 billion to $16 billion in additional monthly goods imports, with about $12 billion in the middle. With exports unchanged, the deficit would rise dollar for dollar. That is simply a back of the envelope calculation, not a measured cost of the ruling: July’s replacement tariffs, changes in the import mix and export responses still need to be accounted for.
Nonetheless, the broader trend remains much better than the August headline suggests. Through the first eight months of 2026, the overall goods-and-services deficit is $138.2 billion—or 19.9 percent—smaller than during the same period last year. Exports are up 11.8 percent; imports are up 4.4 percent. The trade rebalancing has not disappeared.
That is how a temporary investment-heavy deficit becomes the bridge to a smaller trade deficit, a larger industrial base, and a more secure American economy.