
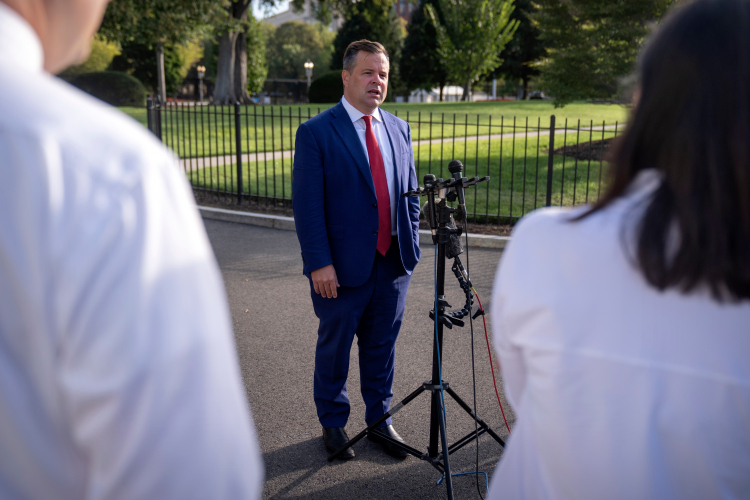
Bill Pulte has moved aggressively since taking over the Federal Housing Finance Agency (FHFA), promising greater competition and lower costs for mortgage borrowers. Each of his initiatives has popular appeal. But taken together, they risk producing serious unintended consequences — leaving taxpayers with more risk while the promised borrower savings may prove illusory.
So far this year, FHFA has introduced lender choice between Classic FICO and VantageScore 4.0, with FICO 10T approved for future use. Just last week, it put FICO and VantageScore on the same loan-level price adjustment grid. And Pulte is now considering whether Fannie Mae and Freddie Mac should abandon the traditional three-bureau credit report in favor of two bureaus—or even one.
Start with credit-score models. Our research at the AEI Housing Center finds that Classic FICO and VantageScore 4.0 are broadly similar in their ability to predict mortgage defaults. But VantageScore scores are about 20 points higher on average. That means the same numerical score does not necessarily represent the same underlying risk across the two models. That difference matters enormously when both scores are run through the same Fannie Mae and Freddie Mac pricing grid.
Because the models have different score distributions, the same borrower can receive a higher VantageScore even though the borrower’s underlying risk has not changed. Applying the same LLPA grid to both models can therefore produce a lower fee without a commensurate reduction in risk. Our analysis estimates that this type of score shopping could reduce GSE loan-level pricing revenue by roughly 13% relative to the baseline.
The result is not just lower GSE fee revenue. It can also mean that Fannie Mae and Freddie Mac are mispricing risk—charging less for loans whose underlying default risk has not fallen—and effectively widening their credit boxes without formally changing underwriting standards. Ultimately, that means more risk is borne by the enterprises—and, given their federal backing, potentially by taxpayers.
Lenders have every reason to embrace the change. If one model gives a borrower a higher score, it can mean the difference between approval or denial or better pricing. Rocket Mortgage and United Wholesale Mortgage, the nation’s two largest mortgage originators by loan count, are already leaning in. Rocket has defaulted to VantageScore for eligible loans because it says the model helps qualify more borrowers, while UWM lets brokers compare FICO and VantageScore and use the more favorable result. Competing lenders have every incentive to do the same.
That means more qualifying borrowers and more originations. But qualification is not the core problem. A shortage of homes—especially starter homes—is what increasingly crowds weaker borrowers out. If the housing supply does not increase correspondingly, more purchasing power or more qualified borrowers chasing the same limited stock of homes will put additional upward pressure on prices. Affordability gains will be short lived.
Now add bureau choice—the ability to choose among Equifax, Experian and TransUnion. Pulte has said FHFA is seriously considering replacing the traditional tri-merge credit report with a bi-merge and is studying the use of a single bureau. The argument is straightforward: why make borrowers pay for three reports if one or two will do?
But our analysis finds that Equifax, Experian and TransUnion can produce materially different scores for the same borrower. Give lenders or borrowers discretion over both the scoring model and the bureau, and the opportunities for shopping multiply. If single-bureau reporting ultimately comes with bureau choice, three scoring models and three bureaus could create as many as nine model-bureau combinations for the most favorable result.
That raises the risk of adverse selection. Investors need confidence that a given credit score reflects comparable underlying risk across loans. If model and bureau shopping weakens that link, they may demand a higher risk premium.
The consumer savings at stake are modest. A tri-merge report typically costs about $80 to $100. By comparison, just a one-basis-point increase in the mortgage rate adds roughly $1,000 in nominal payments over 30 years on a $400,000 mortgage—enough to swamp the upfront savings.
The bigger danger is that this approach spreads beyond FHFA. HUD Secretary Scott Turner and Pulte are increasingly coordinating their housing agendas, and beginning January 1, 2027, the Federal Housing Administration (FHA) will accept VantageScore 4.0 and FICO 10T alongside Classic FICO. VantageScore says it can score 33 million more adults, including nearly 5 million who would clear a 620 mortgage threshold.
That is the attraction: more borrowers who are mortgage-eligible. Because FHA serves lower-score borrowers, FHA will disproportionately benefit from the extra 5 million individuals clearing the 620 threshold. Without more housing supply, added purchasing power can simply push prices higher.
Pulte is right to challenge unnecessary costs and entrenched practices. More competition is generally a good thing. But not when it means lower GSE revenue, weaker risk–based pricing, a widening effective credit box, upward pressure on home prices, and greater taxpayer exposure.
That is the danger here: the gains from easier qualification and lower pricing are privatized, while the losses from mispriced risk are socialized. Saving borrowers a few dollars upfront is no bargain if taxpayers, investors, and future borrowers ultimately bear the larger cost.