
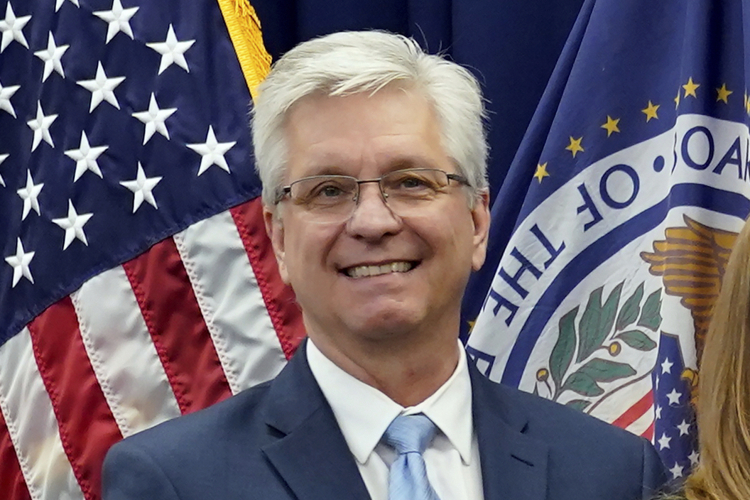
Today’s hotter-than-expected inflation report just handed fresh ammunition to the Federal Reserve’s trigger-happy hawks. Christopher Waller, who is rallying Wall Street for a 50-point hike, is now the poster child.
Let’s be blunt about what Waller wants: A recession to fight an energy-price shock. What the Waller Fed doesn’t understand—where’s Stephen Miran when you need him—is that the energy price shock is already doing the job of the rate hike.
Even the Federal Reserve itself acknowledges that an adverse oil-supply shock simultaneously raises prices and reduces output and employment. Higher oil prices operate much like a tax on households: families spend more filling their tanks and have less money for restaurants, clothing, furniture, vacations, and everything else. Businesses face higher input costs and thinner margins.
To double down on that with an actual rate hike is to risk a recession within a matter of months. Indeed, the Fed is playing with recessionary fire. It wants to burn down Main Street to appease Wall Street.
Waller made his intentions crystal clear before the CPI report was even released. He said he favored at least a quarter-point hike in December even if inflation improved. If core CPI came in at 0.3 percent or higher, he said the Fed should consider a 50-basis-point hike.
Guess what? Core CPI came in at exactly 0.3 percent.
Headline CPI rose 0.4 percent in October, above the 0.3 percent consensus. Core CPI, excluding food and energy, also beat expectations of 0.2 percent. Using the preferred methodology necessitated by last year’s government shutdown, headline inflation is running at roughly 4 percent over the year and core at 2.8 percent.
The hawks therefore have their headline. But look under the hood.
Energy prices are up 20.8 percent over the past year. Gasoline is up an eye-popping 37.4 percent. Food rose 0.5 percent just in October. Airline fares are up nearly 30 percent over the year. Higher energy costs are bleeding through transportation, agriculture, manufacturing, and distribution.
This is precisely what an energy shock looks like.
Yes, core inflation is uncomfortable. Core services rose 0.3 percent in October and 3.5 percent over the year. The inflation pressures have broadened enough that the Fed cannot simply wave them away.
But neither should it pretend that raising the federal funds rate can produce a single extra barrel of crude oil. It cannot reopen the Strait of Hormuz. It cannot lower tanker-insurance premiums. It cannot expand refinery capacity overnight. It cannot put diesel into American trucks.
What a rate hike can do is raise mortgage rates, punish construction, discourage factory investment, squeeze small businesses, strengthen the dollar against American exporters, and eventually put Americans out of work.
That is not theory. It is the transmission mechanism of monetary policy.
As I have noted, the energy shock is already doing much of this work already. That is the central point the lemmings marching toward the rate-hike cliff and lead from behind Kevin Warsh are missing.
There is a very real danger now that any monetary tightening will hit just as the energy shock itself is fading.
Brent crude has already plunged roughly 23 percent from its October 30 peak, falling Tuesday toward $90 a barrel as the risk of further escalation with Iran receded.
That means today’s CPI report is looking backward at an energy shock that financial markets are already telling us may be rolling over. Yet the Fed wants to drive monetary policy by looking in the rearview mirror.
My concern is the collision ahead.
The American economy entered this episode with strong momentum. But an oil shock drains purchasing power in real time. Monetary policy works with a lag. Add another 25 or, God and Kevin Warsh forbid, 50 basis points in December, and the cumulative squeeze from high energy costs, elevated borrowing costs, weaker real purchasing power, and tightening financial conditions could produce a sharp downshift by March or April.
That is the recession danger zone.
And the cruel irony is that it could arrive at almost precisely the moment the energy-driven inflation impulse is washing out of the year-over-year numbers.
We have seen this movie before.
The 1970s were defined by the toxic combination of energy shocks, inflation, weak growth, and stop-go policymaking. In October 1974, President Gerald Ford declared inflation “public enemy number one” and launched his famous Whip Inflation Now campaign. Within months, as recession deepened and unemployment surged, Washington reversed direction and enacted the Tax Reduction Act of 1975 to stimulate demand.
Inflation. Recession. Stimulus. Tightening. Repeat.
That is how policymakers wind up chasing their own tails while workers pay the price.
There is a name for an economy suffering rising prices alongside stagnating growth and weakening employment:
Stagflation.
The Fed should therefore stop treating every inflation print as a nail demanding an interest-rate hammer. And read the damn history books!
Watch inflation expectations. Watch wages. Watch services. Watch whether energy pass-through becomes embedded.
But also watch gasoline. Watch real disposable income. Watch housing. Watch investment. And remember the other half of the dual mandate.
Christopher Waller and the Fed hawks may believe another rate hike demonstrates their credibility. But if they hike America into recession just as oil prices are collapsing, history will call them clueless rather than credible.